
BIL INVESTMENT INSIGHTS
After a volatile week in which stronger-than-expected PMI data fuelled concerns over persistent inflation and higher interest rates, US equities still managed to finish in positive territory. Markets were buoyed by the launch of a new consumer-focused AI agent designed to act as a personal assistant, helping users manage budgets and optimise spending. European equities also edged higher, supported by leading indicators that continue to signal an improving economic backdrop.
Inflation concerns weighed on bond markets, pushing the 10-year US Treasury yield to its highest level since 2007. Fixed income assets found some respite later in the week as crude oil prices declined after reports that Iran had proposed a seven-day framework for reopening the Strait of Hormuz.
By Monday, however, the ongoing stalemate between the US and Iran had triggered a renewed rise in oil prices, reigniting expectations of further rate hikes and putting renewed pressure on both equities and bonds.
Another key development last week was the Trump-Xi summit in Washington. The two leaders agreed to launch a new dialogue on AI, with further discussions scheduled for late November. The two countries also extended their trade truce until 10 January. In addition, China secured lower tariffs on $30bn of goods exported to the United States, with reciprocal measures expected from Beijing. Discussions on increasing the flow of Chinese rare earth exports and easing restrictions on advanced US semiconductor exports made little progress, leaving these issues unresolved for now.
US PMI shoots for the moon
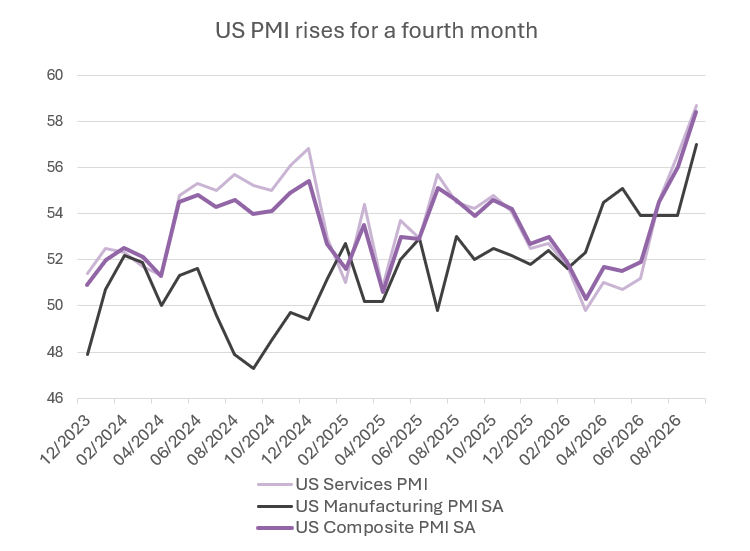
The US Composite PMI rose four a fourth month in a row in September, hitting 58 and indicating the quickest expansion in private-sector activity since July 2021. The gains were driven by the service sector (58.7 vs 56.5), which posted the strongest rise in output for over five years, while manufacturing also accelerated (56.7 vs 53.1). New orders grew further, thanks primarily to robust domestic demand. Companies took on more staff, and at a pace unseen since June 2022. Against this backdrop of robust activity, price pressures intensified, with input costs rising the most since October 2022 mainly due to higher fuel and transport costs though wage pressures were also noted to have picked up in many cases. Selling price inflation also intensified. The market took the data as a cue that the Federal Reserve would need to deliver another rate hike sooner rather than later. Futures now price in around a 70% probability of another 25bp hike late October.
Source: Bloomberg, BIL
Corporate activity rises across the Eurozone, while consumers grow more cautious
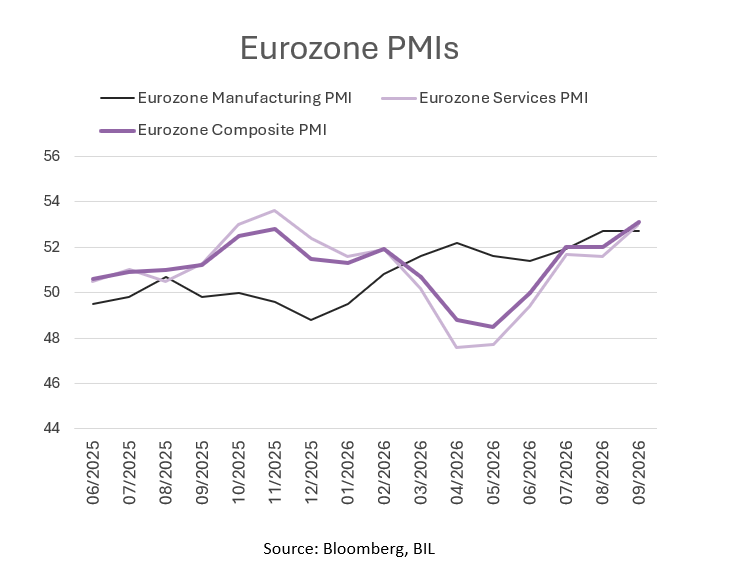
Despite ongoing geopolitical tensions, high energy costs, and rising interest rates, the Eurozone economy keeps pushing forward. The Composite PMI rose to 53.1 in September, up from 52.0 prior, and above market expectations of 51.7, according to flash estimates released on Wednesday. This marks a third month of expansion in business activity. With order books continuing to fill up, the data hints at sustained momentum heading into the fourth quarter, though businesses did express less optimism about the year ahead.
Digging into the details, the services PMI increased to 53, while manufacturing held steady at 52.7. The data confirmed that the fledgling manufacturing upturn is still intact, with output rising to 53.4 - its highest level in 55 months. Growth was supported by a renewed increase in new export orders and an increase in AI and defense spending.
Likely keeping the ECB on its toes, cost inflation accelerated, and output prices rose at a faster pace.
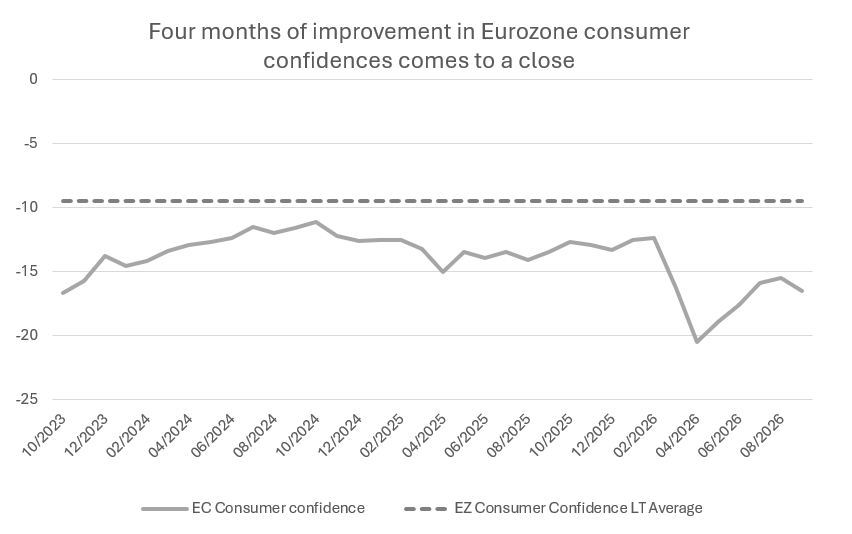
On the consumer side, the latest confidence reading produced by the European Commission weakened. The indicator fell from -15.5 in August to -16.5 in September. Rising prices, largely influenced by the continuation of the conflict in the Middle East, are thought to be a driving factor.
Source: Bloomberg, BIL
Calendar for the week ahead
Monday – BoJ Monetary Policy Meeting Minutes. China Industrial Profits.
Tuesday – Spain Inflation (Preliminary, September), Retail Sales and Business Confidence. Italy Industrial Sales and PPI. Eurozone Economic Sentiment, Consumer Confidence. France Unemployment. US JOLTs Job Openings, Conference Board Consumer Confidence and House Price Index
Wednesday – Japan Retail Sales and Industrial Production. China PMI. Germany Retail Sales and Unemployment. France Inflation Rate (Preliminary, September). Italy Business and Consumer Confidence, Inflation (Preliminary, September). Germany Inflation (Preliminary, September). US GDP Growth (Final, Q2), Personal Income and Spending (August).
Thursday – Japan Tankan Index (Q3), BoJ Summary of Opinions. Eurozone PMI (Final, September). Eurozone, UK Unemployment Rate. France OAT Auction. US Weekly Jobless Claims, ISM Manufacturing PMI (September).
Friday – Japan Consumer Confidence. Eurozone Inflation (Flash, September). Italy Retail Sales. US Nonfarm Payrolls, Unemployment and Average Hourly Earnings.
Sunday – Brazil General Elections. OPEC and non-OPEC Ministerial Meeting.
Disclaimer
All financial data and/or economic information released by this Publication (the “Publication”); (the “Data” or the “Financial data
and/or economic information”), are provided for information purposes only,
without warranty of any kind, including without limitation the warranties of merchantability, fitness for a particular
purpose or warranties and non-infringement of any patent, intellectual property or proprietary rights of any party, and
are not intended for trading purposes. Banque Internationale à Luxembourg SA (the “Bank”) does not guarantee expressly or
impliedly, the sequence, accuracy, adequacy, legality, completeness, reliability, usefulness or timeless of any Data.
All Financial data and/or economic information provided may be delayed or may contain errors or be incomplete.
This disclaimer applies to both isolated and aggregate uses of the Data. All Data is provided on an “as is” basis. None of
the Financial data and/or economic information contained on this Publication constitutes a solicitation, offer, opinion, or
recommendation, a guarantee of results, nor a solicitation by the Bank of an offer to buy or sell any security, products and
services mentioned into it or to make investments. Moreover, none of the Financial data and/or economic information contained on
this Publication provides legal, tax accounting, financial or investment advice or services regarding the profitability or
suitability of any security or investment. This Publication has not been prepared with the aim to take an investor’s particular investment objectives,
financial position or needs into account. It is up to the investor himself to consider whether the Data contained herein this
Publication is appropriate to his needs, financial position and objectives or to seek professional independent advice before making
an investment decision based upon the Data. No investment decision whatsoever may result from solely reading this document. In order
to read and understand the Financial data and/or economic information included in this document, you will need to have knowledge and
experience of financial markets. If this is not the case, please contact your relationship manager. This Publication is prepared by
the Bank and is based on data available to the public and upon information from sources believed to be reliable and accurate, taken from
stock exchanges and third parties. The Bank, including its parent,- subsidiary or affiliate entities, agents, directors, officers,
employees, representatives or suppliers, shall not, directly or indirectly, be liable, in any way, for any: inaccuracies or errors
in or omissions from the Financial data and/or economic information, including but not limited to financial data regardless of the
cause of such or for any investment decision made, action taken, or action not taken of whatever nature in reliance upon any Data
provided herein, nor for any loss or damage, direct or indirect, special or consequential, arising from any use of this Publication
or of its content. This Publication is only valid at the moment of its editing, unless otherwise specified. All Financial data and/or
economic information contained herein can also quickly become out-of- date. All Data is subject to change without notice and may not be
incorporated in any new version of this Publication. The Bank has no obligation to update this Publication upon the availability of new data,
the occurrence of new events and/or other evolutions. Before making an investment decision, the investor must read carefully the terms and
conditions of the documentation relating to the specific products or services. Past performance is no guarantee of future performance.
Products or services described in this Publication may not be available in all countries and may be subject to restrictions in some persons
or in some countries. No part of this Publication may be reproduced, distributed, modified, linked to or used for any public or commercial
purpose without the prior written consent of the Bank. In any case, all Financial data and/or economic information provided on this Publication
are not intended for use by, or distribution to, any person or entity in any jurisdiction or country where such use or distribution would be
contrary to law and/or regulation. If you have obtained this Publication from a source other than the Bank website, be aware that electronic
documentation can be altered subsequent to original distribution.
As economic conditions are subject to change, the information and opinions presented in this outlook are current only as of the date
indicated in the matrix or the publication date. This publication is based on data available to the public and upon information that is
considered as reliable. Even if particular attention has been paid to its content, no guarantee, warranty or representation is given to the
accuracy or completeness thereof. Banque Internationale à Luxembourg cannot be held liable or responsible with respect to the information
expressed herein. This document has been prepared only for information purposes and does not constitute an offer or invitation to make investments.
It is up to investors themselves to consider whether the information contained herein is appropriate to their needs and objectives or to seek advice
before making an investment decision based upon this information. Banque Internationale à Luxembourg accepts no liability whatsoever for any investment
decisions of whatever nature by the user of this publication, which are in any way based on this publication, nor for any loss or damage arising
from any use of this publication or its content. This publication, prepared by Banque Internationale à Luxembourg (BIL), may not be copied or
duplicated in any form whatsoever or redistributed without the prior written consent of BIL 69, route d’Esch ı L-2953 Luxembourg ı
RCS Luxembourg B-6307 ı Tel. +352 4590 6699 ı www.bil.com.
Read more