
BIL INVESTMENT INSIGHTS
As the earnings season reaches its halfway mark, corporate results continue to highlight a divergence between the US and Europe. Approximately four out of five US companies have surpassed analyst expectations, supported by solid margins and broadly resilient earnings growth. In Europe, around 48% have delivered positive earnings surprises, with results remaining uneven across sectors. The disparity reinforces the view that the US earnings recovery remains stronger and more broad-based than that seen in Europe.
Yet strong earnings have not necessarily translated into stronger equity markets. Investor reactions to earnings beats have been subdued, suggesting that elevated expectations are limiting the scope for positive surprises to drive stock prices materially higher. Markets faced renewed pressure last week after disappointing results from several technology companies catalysed a broader risk-off move, that pushed investors toward Treasuries and other traditional safe havens.
Also in the AI sphere, Anthropic, the company behind Claude AI models, has formally moved ahead with plans for its IPO under the ticker ANT. Media reports indicate the company could command a valuation of between USD 1.5 trillion and USD 2 trillion, potentially making the offering one of the most significant public listings ever. The IPO is expected to serve as a key litmus test of investor conviction in the AI investment story and the sector's lofty valuations more broadly. While no official date has been communicated, reports indicate the stock could begin trading as soon as November 16, 2026.
This week, attention will be firmly focused on the US midterm elections, to be held on Tuesday. Prediction markets currently assign Democrats a roughly 73% probability of gaining control of the Senate and a 94% probability of winning the House. However, political events, from Brexit to Brazil's presidential election, serve as reminders that electoral outcomes do not always align with expectations.
Regardless of the result, the scope for sweeping legislative change is likely to remain limited. With neither party expected to secure a veto-proof two-thirds majority in either chamber, significant shifts in fiscal, tax or regulatory policy would still face constraints.
Historically, US equities have tended to generate positive returns in the three months following midterm elections. Investors should nevertheless be cautious about relying too heavily on historical patterns. Geopolitical risks remain elevated, particularly given the possibility of renewed military action in Iran after the election, which could have important implications for market sentiment and energy prices. Furthermore, US government funding is set to expire on December 11, and political wrangling may ensue, with the Republicans keen to enhance defense spending and potentially address the debt limit.
Market Snapshot
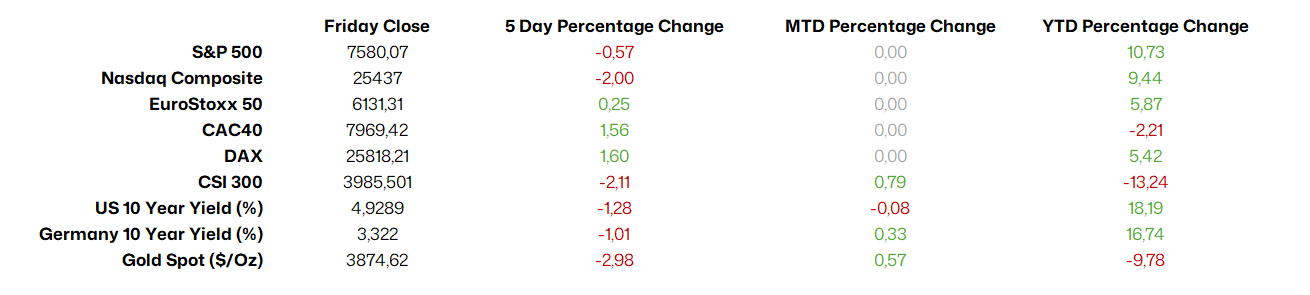
Source: Bloomberg, BIL as of 2 November 2026
Macro Snapshot
Major central banks keep rates on hold, but leave the door open to further tightening
US
The US Federal Reserve left its policy rate unchanged at 3.75-4.00% at its October FOMC meeting, in line with market expectations. The decision, the last before the US midterm elections, was backed by eight of the ten policymakers, while two members voted in favour of a rate increase.
During the press conference, Fed Chair Kevin Warsh highlighted the continued resilience of the US economy, pointing to strong capital expenditure, resilient household spending and a steady labour market. Against this backdrop, inflationary pressures have re-emerged, with headline CPI accelerating to 3.7% in September.
The accompanying policy statement acknowledged that inflation remains above target and reiterated the Fed's commitment to restoring price stability. Policymakers stressed that additional data would help determine the appropriate policy stance required to bring inflation sustainably back to the 2% objective.
Warsh struck a wait-and-see tone, noting that the Fed would benefit from the "information-rich interval" between now and the December meeting. Developments in the Middle East will be a key factor to monitor, particularly given that the recent pickup in inflation has been largely energy-driven.
The next FOMC meeting is scheduled for 8-9 December and will deliver the Fed's final rate decision of the year. Financial markets expect a rate hike at that meeting, and then one more before June 2027.
Warsh also announced adjustments to the FOMC calendar. While the committee will continue to meet eight times per year, one meeting in the second half of next year will be dedicated to longer-term strategic discussions rather than policy decisions. From 2028 onwards, two meetings annually will be allocated to strategy reviews, reducing the number of rate-setting meetings from eight to six.
Eurozone
The European Central Bank left interest rates unchanged at its October meeting, in line with expectations, while maintaining a cautious stance on the inflation outlook.
- Deposit facility rate: 2.5%
- Main refinancing operations: 2.65%
- Marginal lending facility: 2.9%
ECB President Christine Lagarde stressed that policymakers remain “very attentive” to inflation risks but do not currently see a material threat of second-round effects, such as excessive wage growth or a sharp rise in inflation expectations. She acknowledged that financing conditions have tightened since the previous meeting, a development that is likely to weigh on both economic growth and inflation, while elevated energy costs continue to dent consumer confidence.
Nevertheless, Lagarde reiterated that the ECB’s policy direction remains “clear”, keeping the possibility of further rate increases on the table. Overall, markets interpreted the message as somewhat dovish, with some analysts viewing it as a step towards the eventual end of the tightening cycle. Even so, traders continue to price in around two additional quarter-point rate hikes by June 2027, including a high probability of a move in December.
Attention is also turning to leadership changes, with Lagarde set to step down from her role in February. Her term was officially supposed to stretch until October. Former central bank governors Pablo Hernández de Cos (Spain) and Klaas Knot (the Netherlands) are leading contenders to succeed her.
Japan
On Friday, the Bank of Japan delivered what was perceived as a hawkish pause. While rates were left unchanged at 1.25%, Governor Ueda signalled that a December rate hike remains possible after stating that underlying inflation has reached the 2% target. On first instance, the yen gained, but it later softened as the press conference was rather vague about the timing of future moves.
Investors caught off guard after Lula wins a fourth term as President of Brazil
Luiz Inácio Lula da Silva, widely known as Lula, secured his fourth non-consecutive term as President of Brazil after defeating Senator Flávio Bolsonaro in a runoff election, winning 51.8% of the vote to Bolsonaro’s 48.2%.
The result was historically significant, marking the first time since Brazil’s return to democracy in the 1980s that a candidate who lost the first round went on to win in the second. The surprise was visible in the severe market reaction. Investors have expressed concern that Lula will not aggressively address Brazil’s worsening fiscal situation, characterised by deficits of around 10% of GDP, public debt exceeding 80% of GDP, high interest rates, and heavily indebted households. São Paulo’s Bovespa index fell 13.9%, with financial stocks suffering the largest losses, while the Brazilian real dropped 8%, its sharpest decline since 1999.
Investors had largely expected Bolsonaro, who led after the first round on October 4, to pursue more business-friendly and fiscally orthodox policies. In contrast, Lula has proposed only modest fiscal adjustments, while also making costly campaign promises, including free weekend public transport, debt forgiveness for individuals, and increased welfare payments.
While creating economic growth and reducing inequality are likely to be higher on Lula’s agenda than fiscal austerity, he may nevertheless be constrained by political realities. Brazil’s Senate has shifted significantly to the right following strong gains by Bolsonaro’s party. As a result, he will need to work closely with centrist and right-wing parties to advance his agenda.
Investor attention is now laser-focused on Lula’s choice of finance minister and whether he can present a credible strategy to stabilise the debt-to-GDP ratio. If he manages this, it could help lower interest rates and give more margin when balancing budgets. Meanwhile, after initially threatening to contest the outcome, Bolsonaro ultimately accepted the result, with his Liberal Party formally conceding defeat to President-elect Lula.
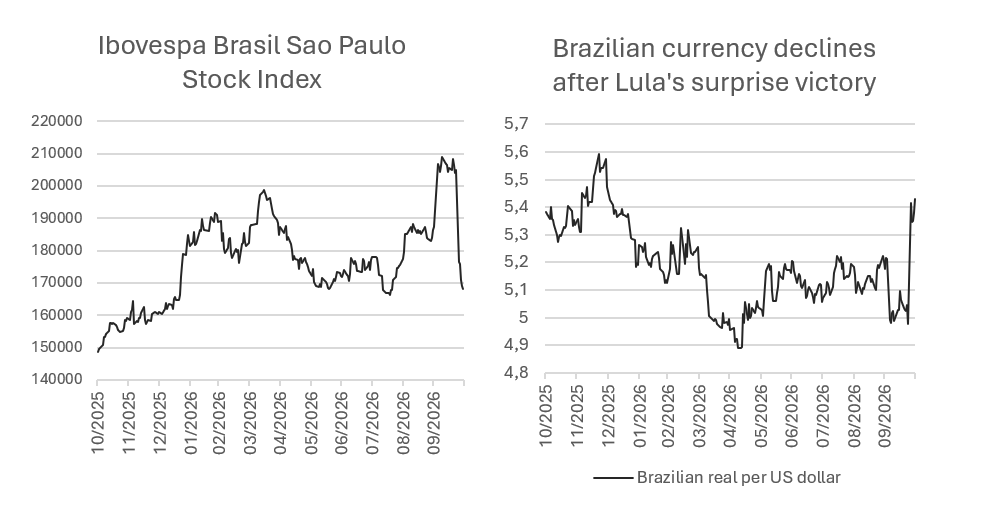
Source: Bloomberg, BIL as of 30/10/26. Past performance is not a reliable indicator of future returns.
The consumer mood darkens across the Eurozone
The clocks have gone back, the evenings are getting darker, and consumers are feeling evermore gloomy, according to the latest European Commission data. Euro Area consumer confidence declined to -17.9 in October, its lowest level since May, reflecting ongoing concerns about persistent inflation, elevated global oil prices, and the likelihood of higher interest rates. With the indicator averaging -9.51 points since 1985, current levels suggest that households remain significantly more downbeat than normal. Consumer sentiment has struggled to recover since the Covid-19 pandemic, with successive shocks, including the surge in inflation and the economic fallout from the war in Ukraine, continuing to weigh on household confidence and spending intentions across the region.
The deterioration was particularly pronounced in France, where widespread protests that began as student demonstrations in suburban Paris over school conditions evolved into a broader movement opposing the government’s economic policies. Against this backdrop social unrest, consumer confidence fell by five points to 80 in October, its lowest level since June 2013 and well below the long-term average of 100. French households expressed growing concerns about rising prices and a renewed risk of unemployment, while a sell-off in government bonds heightened worries about the country’s fiscal outlook. Data released Wednesday showed that the number of unemployed people in the country rose to the highest level in five years in September.
With major demonstrations and strikes scheduled for 5 November and backed by France’s largest trade unions, the unrest appears set to continue, posing an additional challenge to economic confidence in the months ahead. This, coupled with increasing political uncertainty as the 2027 Presidential election approaches, is likely to weigh on household spending in the months ahead, adding further downside risks to an already-tepid growth outlook.
In Germany, the GfK Consumer Climate Indicator dropped to -30.6 in October from -26.8. The decline was largely driven by a sharp fall in income expectations, which dropped 16.7 points to -15.0, as households grew increasingly concerned that high energy costs would erode purchasing power. At the same time, willingness to save rose to 21.5, its highest level since the 2008 financial crisis, reflecting greater financial caution. Despite weaker consumer sentiment, economic expectations improved slightly for a fifth consecutive month, following stronger-than-expected economic performance during the first half of 2026.
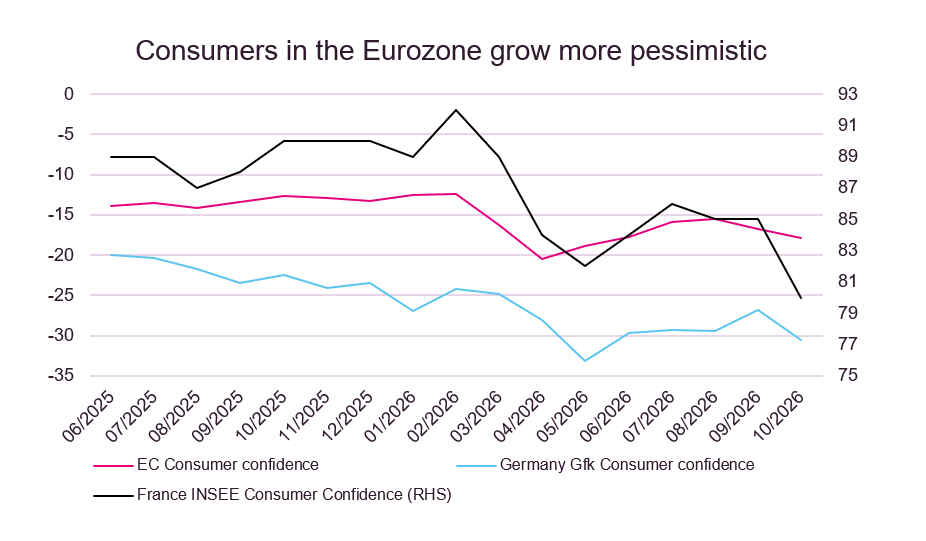
Source: Bloomberg, BIL
US consumers, on the other hand, are feeling more upbeat this Fall. The Conference Board’s confidence index rose sharply in October, reaching 91.8, with households adopting a more favourable view on the labour market and business conditions.
Calendar for the week ahead
Monday – China Manufacturing PMI. Germany Retail Sales. Eurozone Manufacturing PMI (Final, October). US ISM Manufacturing PMI.
Tuesday – US JOLTs Job Openings and Factory Orders. US Midterm Elections.
Wednesday – Eurozone Composite PMI (Final, October). Eurozone Inflation (Flash, October). US ISM Services PMI (October).
Thursday – Germany Factory Orders. France Industrial Production. Eurozone PPI. Bank of England Monetary Policy Committee. US Weekly Jobless Claims.
Friday – Germany and Spain Industrial Production.
Disclaimer
All financial data and/or economic information released by this Publication (the “Publication”); (the “Data” or the “Financial data
and/or economic information”), are provided for information purposes only,
without warranty of any kind, including without limitation the warranties of merchantability, fitness for a particular
purpose or warranties and non-infringement of any patent, intellectual property or proprietary rights of any party, and
are not intended for trading purposes. Banque Internationale à Luxembourg SA (the “Bank”) does not guarantee expressly or
impliedly, the sequence, accuracy, adequacy, legality, completeness, reliability, usefulness or timeless of any Data.
All Financial data and/or economic information provided may be delayed or may contain errors or be incomplete.
This disclaimer applies to both isolated and aggregate uses of the Data. All Data is provided on an “as is” basis. None of
the Financial data and/or economic information contained on this Publication constitutes a solicitation, offer, opinion, or
recommendation, a guarantee of results, nor a solicitation by the Bank of an offer to buy or sell any security, products and
services mentioned into it or to make investments. Moreover, none of the Financial data and/or economic information contained on
this Publication provides legal, tax accounting, financial or investment advice or services regarding the profitability or
suitability of any security or investment. This Publication has not been prepared with the aim to take an investor’s particular investment objectives,
financial position or needs into account. It is up to the investor himself to consider whether the Data contained herein this
Publication is appropriate to his needs, financial position and objectives or to seek professional independent advice before making
an investment decision based upon the Data. No investment decision whatsoever may result from solely reading this document. In order
to read and understand the Financial data and/or economic information included in this document, you will need to have knowledge and
experience of financial markets. If this is not the case, please contact your relationship manager. This Publication is prepared by
the Bank and is based on data available to the public and upon information from sources believed to be reliable and accurate, taken from
stock exchanges and third parties. The Bank, including its parent,- subsidiary or affiliate entities, agents, directors, officers,
employees, representatives or suppliers, shall not, directly or indirectly, be liable, in any way, for any: inaccuracies or errors
in or omissions from the Financial data and/or economic information, including but not limited to financial data regardless of the
cause of such or for any investment decision made, action taken, or action not taken of whatever nature in reliance upon any Data
provided herein, nor for any loss or damage, direct or indirect, special or consequential, arising from any use of this Publication
or of its content. This Publication is only valid at the moment of its editing, unless otherwise specified. All Financial data and/or
economic information contained herein can also quickly become out-of- date. All Data is subject to change without notice and may not be
incorporated in any new version of this Publication. The Bank has no obligation to update this Publication upon the availability of new data,
the occurrence of new events and/or other evolutions. Before making an investment decision, the investor must read carefully the terms and
conditions of the documentation relating to the specific products or services. Past performance is no guarantee of future performance.
Products or services described in this Publication may not be available in all countries and may be subject to restrictions in some persons
or in some countries. No part of this Publication may be reproduced, distributed, modified, linked to or used for any public or commercial
purpose without the prior written consent of the Bank. In any case, all Financial data and/or economic information provided on this Publication
are not intended for use by, or distribution to, any person or entity in any jurisdiction or country where such use or distribution would be
contrary to law and/or regulation. If you have obtained this Publication from a source other than the Bank website, be aware that electronic
documentation can be altered subsequent to original distribution.
As economic conditions are subject to change, the information and opinions presented in this outlook are current only as of the date
indicated in the matrix or the publication date. This publication is based on data available to the public and upon information that is
considered as reliable. Even if particular attention has been paid to its content, no guarantee, warranty or representation is given to the
accuracy or completeness thereof. Banque Internationale à Luxembourg cannot be held liable or responsible with respect to the information
expressed herein. This document has been prepared only for information purposes and does not constitute an offer or invitation to make investments.
It is up to investors themselves to consider whether the information contained herein is appropriate to their needs and objectives or to seek advice
before making an investment decision based upon this information. Banque Internationale à Luxembourg accepts no liability whatsoever for any investment
decisions of whatever nature by the user of this publication, which are in any way based on this publication, nor for any loss or damage arising
from any use of this publication or its content. This publication, prepared by Banque Internationale à Luxembourg (BIL), may not be copied or
duplicated in any form whatsoever or redistributed without the prior written consent of BIL 69, route d’Esch ı L-2953 Luxembourg ı
RCS Luxembourg B-6307 ı Tel. +352 4590 6699 ı www.bil.com.
Read more